Getting started with a self managed super fund
A plain English guide for families considering property through super, covering what an SMSF is, what it costs and the checks to make before you move a dollar.
By Natalie Hawkes, Mortgage Broker 7 November 2026 7 minute read
You may have heard that a self-managed super fund, or SMSF, can buy property. Before looking at buildings or loan amounts, it helps to understand what running your own fund involves and whether it fits your retirement plans.
An SMSF can give you more say over your super investments. It also puts the responsibility for the fund in your hands. Start by checking suitability, costs and insurance before setting up a fund or transferring super.1,2
What is an SMSF
It is a super fund run by its members for their retirement. Generally, members are either trustees themselves or directors of a company that acts as trustee. A trustee is the person or company legally responsible for the fund. An SMSF can have up to six members.3
It is still your retirement money
Moving super into an SMSF does not make it available for everyday spending. The usual rules about when you can access super still apply. The fund's money and investments must be kept separate from your personal and business finances.4
Could an SMSF suit your family
It may be worth exploring if you want more control, have the time and ability to stay involved, and understand the responsibilities. Your retirement goals, investment approach and willingness to manage the fund all matter.2
It may be a poor fit if you want a hands-off arrangement, the costs would take too much of your balance, or the proposed property would leave little cash for expenses.
A higher super balance alone does not establish that an SMSF is suitable.
Can my partner and I combine our super
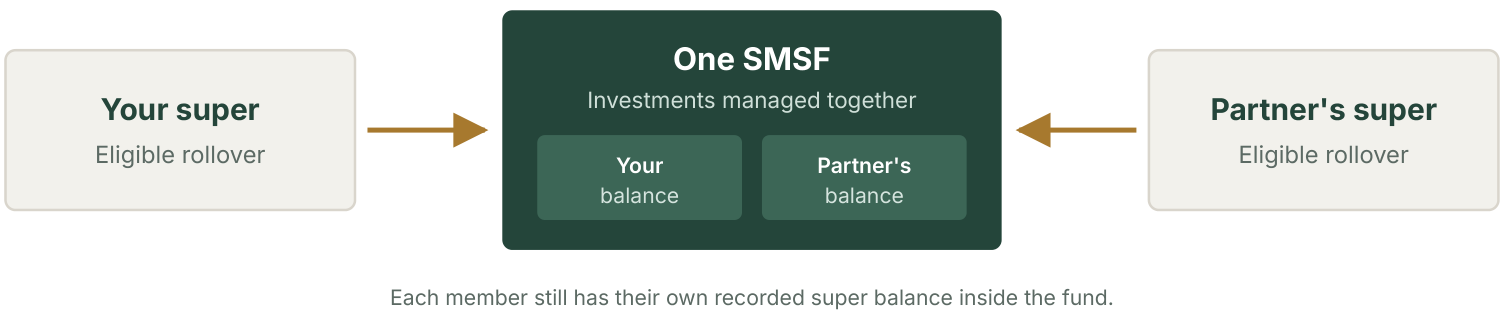
You can generally be members of the same SMSF if you meet the eligibility and trustee requirements. Each person can roll eligible existing super into the fund. Investments can be managed together, but the fund still records each member's individual benefits. It does not become one jointly owned personal account.3,5
You both need to understand the arrangement and agree on how it will be managed. Different retirement dates, a relationship breakdown, illness or death can affect the fund. Plan for those possibilities at the beginning.1
How much super do we need
There is no single balance that makes an SMSF suitable for everyone. Fixed fees have a bigger effect on a smaller fund. Compare the full costs with your existing super and consider future contributions, investment risks and how much cash the fund needs.2
For a property purchase, your balance must cover more than a deposit. Allow for setup and advice, duty, legal and loan costs, any GST funding requirements and a sensible cash buffer. Lenders also have their own requirements.6
Always seek advice from your accountant or financial adviser about tax and costs.
What costs should we allow for
At the start. Advice, the trust deed and establishment, and company registration if using a corporate trustee. A property loan may also require a separate holding trust and additional legal work.3,6
Each year. Accounting, an independent audit, administration, the ATO supervisory levy, applicable company fees, insurance and investment expenses. Property adds its own expenses and borrowing costs. Ask for itemised quotes; a cheap setup price does not show the ongoing cost.1,3,6,7
Emma and James check the numbers
Fictional example only. These amounts are planning assumptions, not recommended balances, fee quotes or a loan offer.
Emma and James have $240,000 and $210,000 in separate super funds. They run a small business and are interested in buying commercial premises. Their first step is to explore whether an SMSF would suit their retirement plans, rather than commit to a property.
For an initial budget, they assume $450,000 could be available after eligible rollovers. Their advisers still need to check insurance, fees and the actual amounts available to transfer.
| THEIR EARLY PLANNING BUDGET | ILLUSTRATIVE AMOUNT |
|---|---|
| Combined super before costs | $450,000 |
| Setup and initial advice allowance | $8,000 |
| Proposed property deposit | $240,000 |
| Property purchase and loan costs allowance | $42,000 |
| Remaining for cash and other investments | $160,000 |
They also assume annual fund administration and compliance costs of $4,000. That is about 0.9% of the original $450,000 balance each year, before property expenses, loan costs, insurance, investment fees and tax. The same $4,000 would be 2% of a $200,000 balance.
This shows why comparing costs as a percentage can help. It does not tell them whether the SMSF will outperform their current funds.
The decision comes after the checks
Their financial adviser reviews suitability, alternatives and existing insurance. Their accountant checks tax and administration costs. Their broker explores possible loan terms and tests repayments against expected rent, expenses and contributions. Their solicitor checks the property contract and ownership structure.
Emma and James decide to continue investigating, without signing a purchase contract yet. They still need to test vacancy, higher interest rates and whether the investment leaves enough flexibility for both members' retirement needs.
The $42,000 allowance is not a stamp duty or GST estimate. Actual costs depend on the property, location, transaction and providers. No purchase price or approved loan amount is assumed. The remaining $160,000 is not a prescribed cash reserve. This example does not establish suitability or finance approval.
Always seek advice from your accountant or financial adviser about tax and costs.
Frequently asked questions
Q Do I have to be self employed to have an SMSF?
No. The name refers to managing the fund yourself, rather than your employment status. Eligibility and trustee requirements still apply.3
Q Can I pay someone to manage the paperwork?
Yes. Accountants and administrators can help. You still retain responsibility as trustee or director; outsourcing the work does not remove that duty. An independent approved SMSF auditor is required each year.1,7,8
Q Does an SMSF have to buy property?
No. Its investments must follow the fund's investment strategy and super rules. Property is one possible investment. Existing retail or industry funds may also offer investment choices that meet your needs.1,4
Q Can an SMSF borrow to buy property?
Potentially, under strict rules. A limited recourse borrowing arrangement, or LRBA, is a specialist structure generally involving a single asset and a separate holding trust. Finance approval is a separate question from whether the strategy suits you.6
Q Can my business rent a commercial property owned by the fund?
Potentially, where it qualifies as business real property and the arrangement meets the rules. A genuine commercial lease and market rent are important. Have the property's use and proposed lease checked.6
Where to begin
Gather your information
Current super statements, insurance details, contributions, your retirement goals and any property or rent information. An initial discussion does not require you to move your super.
Check suitability first
An appropriately authorised financial adviser can assess the SMSF strategy. Your accountant and solicitor address tax, administration and legal requirements. If you proceed, the setup includes the trustee structure, trust deed, registration, bank account, electronic service address and investment strategy before investing.4,8
Explore lending with Leverage Financial Group
We can help assess available SMSF property finance and explain lender requirements, working alongside your other advisers. Get the purchaser and borrowing structure checked before signing a contract.6
General information only. This article does not consider your objectives, financial situation or needs and is not personal financial, tax or legal advice. Obtain advice from appropriately qualified professionals before establishing an SMSF, transferring super or buying property. Rules and lender policies can change. Natalie Hawkes is Credit Representative 479789 of Australian Finance Group Ltd, Australian Credit Licence 389087.
SOURCES · CHECKED 7 NOVEMBER 2026
1. Moneysmart: Self managed super fund
2. ASIC: Guidance on SMSF advice and balances
3. ATO: Trustee structures and establishment costs
4. ATO: Starting a self managed super fund
5. ATO: Contributions and rollovers
6. Moneysmart: SMSFs and property
7. ATO: Running an SMSF, fast facts
8. ATO: How a professional can help